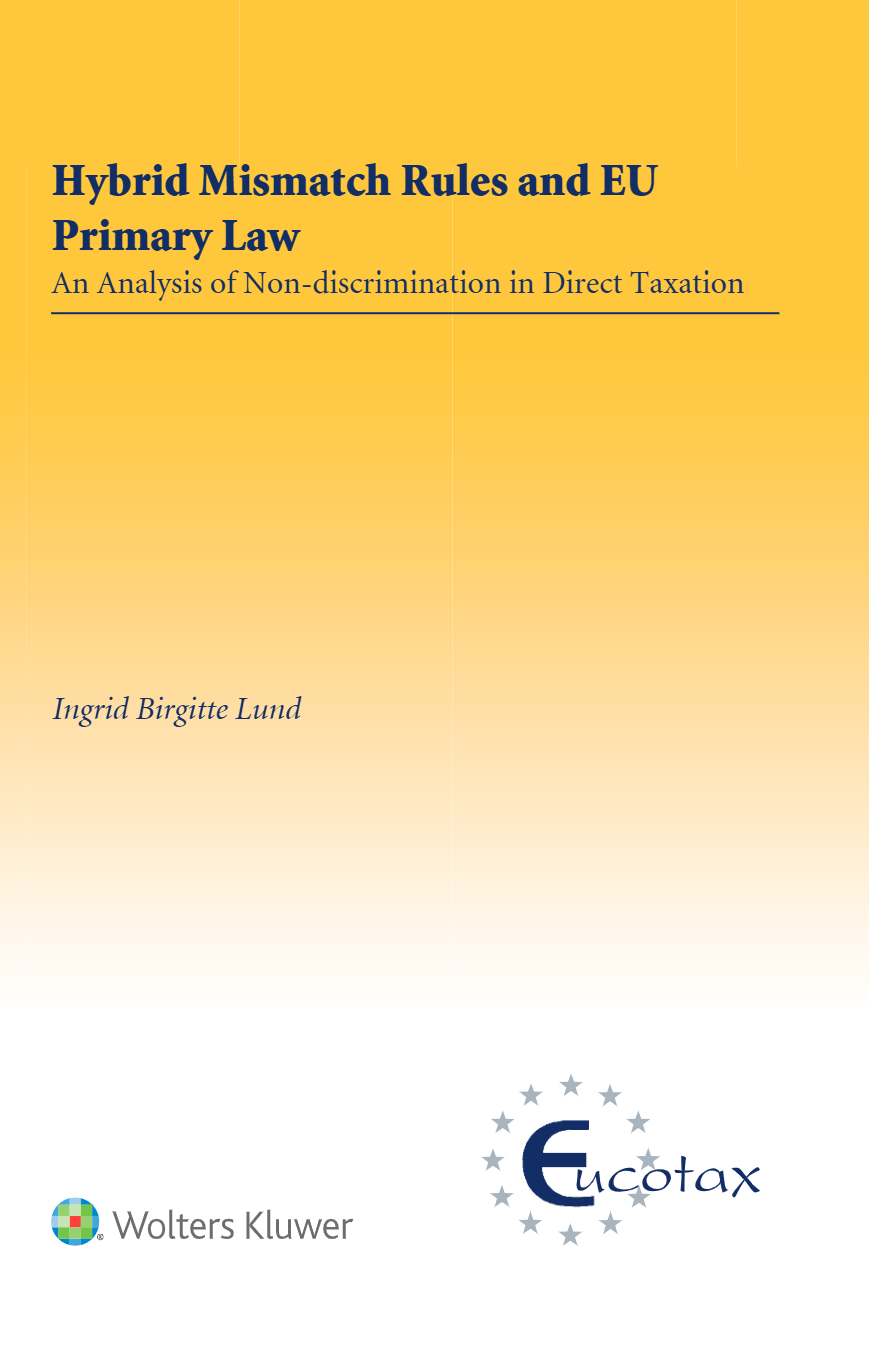
Hybrid Mismatch Rules and EU Primary Law is a book exploring whether the transposed national hybrid mismatch rules, as enacted based on Articles 9, 9a, and 9b of the EU Anti-Tax Avoidance Directive (ATAD), infringe on taxpayers’ right to free movement under the fundamental freedoms and clarifies the extent of the protection these freedoms afford in direct tax cases. Hybrid mismatch rules obligate Member States to alter the tax treatment for cross-border transactions to prevent non-taxation or double non-taxation which may occur when a transaction is not only deductible for the payer but also deductible or not taxed as income for the payee.